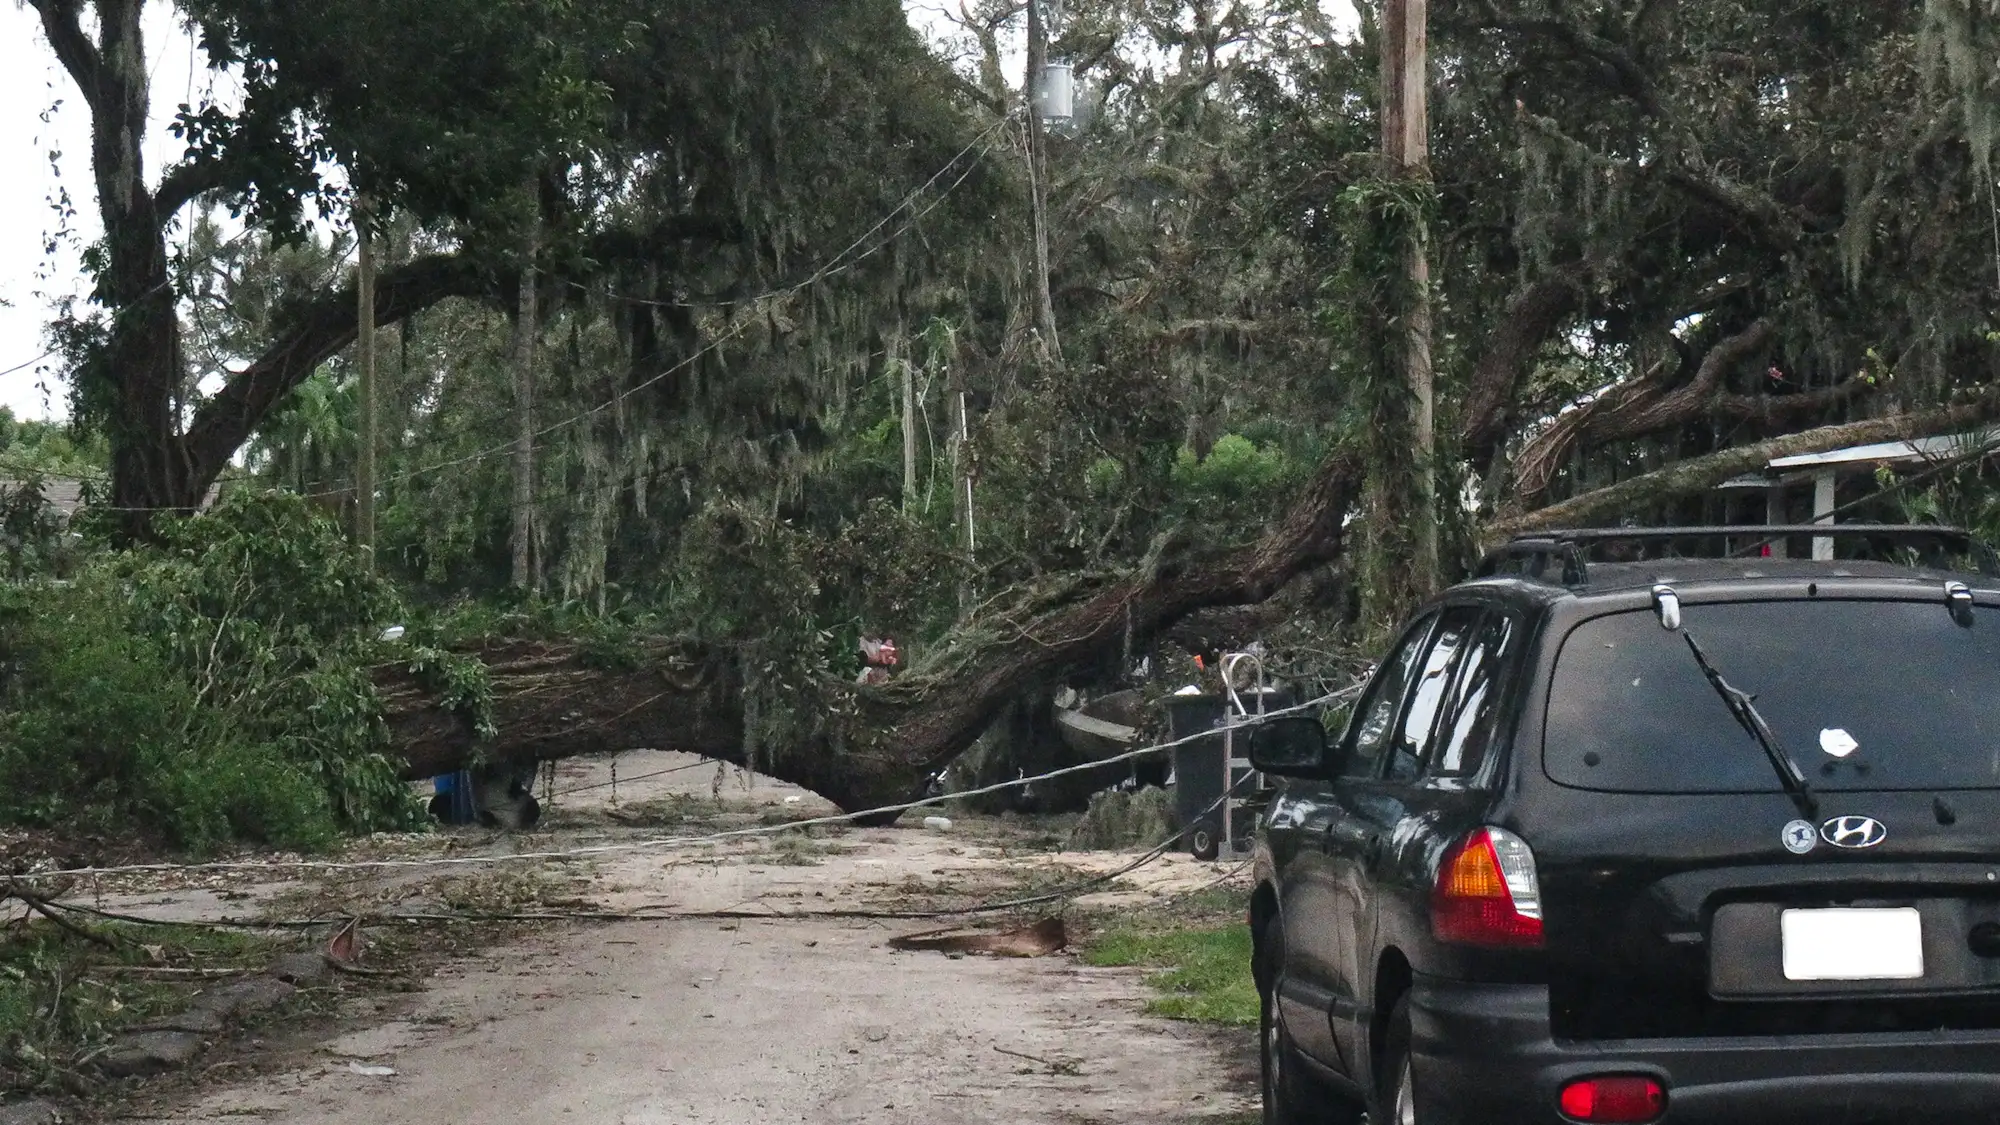
Insurance claims · Lee County, Florida
We document it.
We don't adjust it.
In Florida a roofing contractor is not permitted to negotiate your insurance claim. What a contractor can do — and what we'll make sure gets done properly — is photograph the damage, measure it, and write it up, so that whoever does handle the claim is working from something solid.
If a roofer has offered to "handle your claim" or waive your deductible, read the section below before you sign anything.
- Free, with no obligation
- Written report with photos
- Office on Cypress Lake Drive
Photographed properly
Wide and close, located and dated.
Measured and scoped
A real scope of work, not a one-line estimate.
On site with your adjuster
We'll answer roof questions while they're there.
Straight about the limits
We'll tell you what we're not allowed to do.
The part most sites leave out
What Florida law says a roofer can do
After a storm, a certain kind of contractor will offer to "handle the whole claim for you". It sounds like a favour. It's illegal.
s. 626.854(16), Florida Statutes is explicit: a contractor licensed under part I of chapter 489, or a subcontractor of that licensee, "may not advertise, solicit, offer to handle, handle, or perform public adjuster services… unless licensed and compliant as a public adjuster". Public adjuster services means negotiating or effecting the settlement of a claim on behalf of an insured. The Department of Financial Services can fine people who do it anyway.
And s. 489.147 — "Prohibited property insurance practices" — makes it unlawful for a contractor to offer a homeowner a rebate, gift, gift card, cash, coupon or waiver of an insurance deductible in exchange for allowing a roof inspection or making a claim. Knowingly paying, waiving or rebating a deductible with intent to injure, defraud or deceive is insurance fraud and a third-degree felony.
We're telling you this on our own services page because it's the single most useful thing a homeowner can know before a stranger knocks on the door after a hurricane.
Three people can act on your claim.
You. No licence needed to represent yourself, and for a straightforward claim that is often entirely sufficient.
A licensed public adjuster. Regulated by the Department of Financial Services, with fees capped by statute. Ask for the licence number and check it.
An attorney. Usually where coverage itself is being disputed rather than the amount.
We don't take referral fees from any of them, which is why we can tell you when we think you don't need one.
What we do instead
The evidence, done properly.
An adjuster can only work from what's in front of them. Most underpaid claims are under-documented rather than unfairly handled.
Inspect and photograph
Every damaged area, wide shot and close shot, so the location on the roof is never in question. Dated, captioned, and delivered to you as files you own.
Measure and scope
Slope areas, courses affected, linear feet of flashing or valley, the lot. A scope of work that lists what has to be done and why, rather than a single number on a page.
Be there for the adjuster's inspection
If you'd like us on site when your adjuster comes, we'll be there to answer technical questions about the roof. Answering questions is not negotiating, and we'll keep that line clear.
Repair or rebuild what's approved
Once the claim is settled, the work should be done at the price you were quoted — not at whatever number the settlement happened to land on. Get that agreed in writing before the claim starts, not after.
The deadlines, because they're shorter than people think
Under s. 627.70132, Florida Statutes, notice of a claim or a reopened claim has to reach your insurer within one year of the date of loss. A supplemental claim — the one you file when the full extent turns out to be worse than first thought — has 18 months.
For a hurricane, the clock starts at landfall. For a tornado, windstorm, severe rain or other weather event, it starts on the date NOAA verifies. Not the date you noticed the stain on the ceiling.
This is the practical argument for getting a roof looked at after a storm even when it looks fine from the ground: a dated inspection report with photographs, taken in week two, is worth a great deal in month fourteen.
Insurance claims
The questions worth asking any roofer
Can a roofer handle my insurance claim for me?
No — and this is worth knowing before somebody offers. s. 626.854(16), Florida Statutes says a licensed contractor, or a subcontractor of one, "may not advertise, solicit, offer to handle, handle, or perform public adjuster services" unless they are licensed as a public adjuster. Negotiating your claim is public adjusting. Any roofer who offers to do it is either licensed as an adjuster as well — which is rare and which they should be able to prove — or telling you something that isn't true.
So what can you actually do?
Document. A contractor inspects the roof, photographs what's wrong, measures it, and writes a scope of work and a price for repairing it. That part is squarely a contractor's job, and we'll arrange it. They can also be on site when your adjuster inspects, to answer technical questions about the roof while they're there. What we can't do is argue about coverage or amount on your behalf.
Who can negotiate a claim, then?
You can, for yourself. A licensed public adjuster can, for a fee set by statute. An attorney can. We're happy to explain which of those is likely to be worth it in your situation, and we don't take referral arrangements that would make that advice less than straight.
Will you waive my deductible or 'take care of it' in the price?
No, and neither should anyone else. Under s. 489.147, Florida Statutes it is unlawful for a contractor to knowingly pay, waive or rebate all or part of an insurance deductible with intent to injure, defraud or deceive — that's insurance fraud, a third-degree felony. The same statute prohibits offering a rebate, gift card, cash or other thing of value in exchange for a roof inspection or a claim. If a roofer offers you any of that, they've just told you how they do business.
My claim was denied. Is that the end of it?
Not necessarily, and a denial is not always about whether the damage is real. It can turn on cause, date of loss, exclusions, or the quality of the documentation on file. Getting the roof properly documented is the part we can help with. What happens with it afterwards is a conversation for you, a public adjuster, or an attorney.
Start here
Get the roof documented first.
Whatever happens with a claim afterwards, you want photographs and a written condition report taken before anyone argues about anything. That is what this books, and it costs you nothing.
Get it documented while it's fresh.
Free inspection, photographs you own, and a written scope of work you can hand to anyone.
Book a free inspection